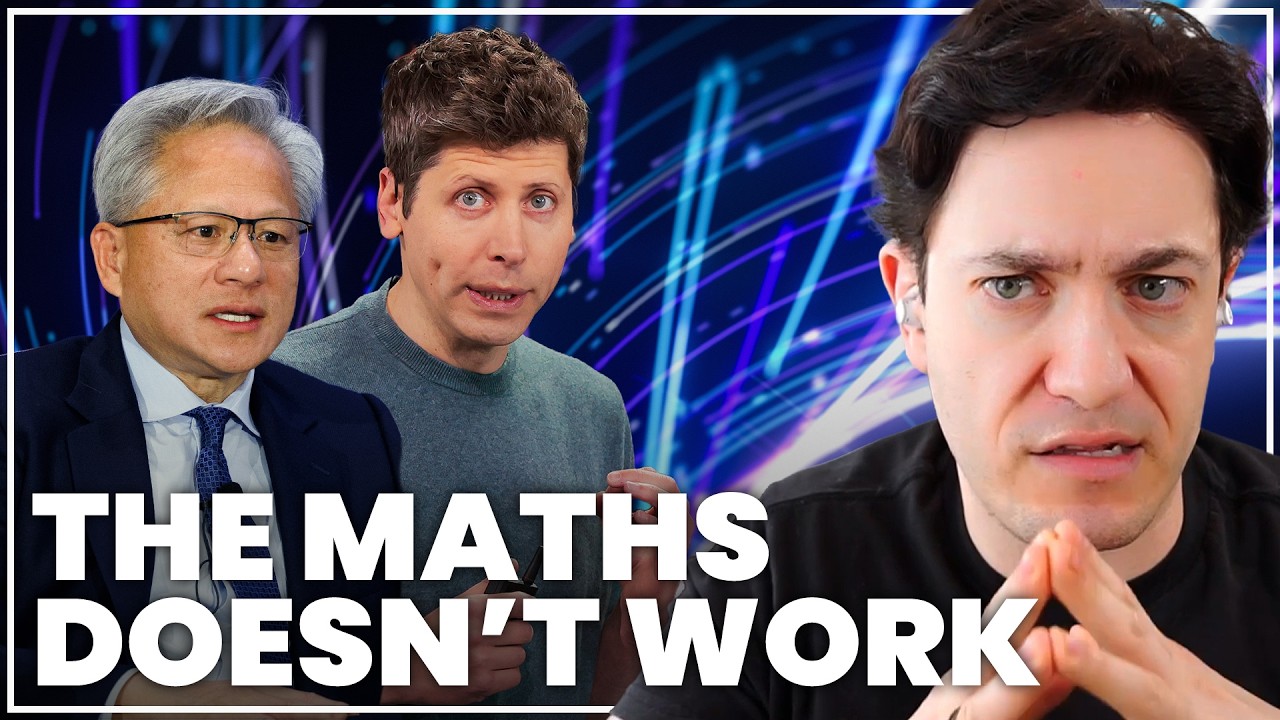
Ed Zitron told The Tech Report that something profound has changed in AI finance, and he put the number on debt.
CoreWeave's fixed-term loans touched a 16% yield this week, Zitron said, with every tranche now above 14% and one above 15.3% as of the recording.
That is personal loan pricing, not infrastructure credit, and Zitron argued it reprices all neocloud borrowing. He said most neoclouds and data center special purpose vehicles will now face 10% to 13% if they try to raise anything at all. A brand new neocloud called VA is already trying to raise a leveraged loan above 11%, he said, with JPMorgan and Goldman Sachs trying to sell the debt rather than hold it.
The signal, in his telling, is not a stock wobble. It is the bond market deciding the AI buildout may not pay. Zitron said he has spent months in debt markets precisely because equities are emotional and easier to move with a headline from Nvidia chief Jensen Huang. Debt, he argued, boils slower and is harder to put back in the cup.
The math he laid out was blunt. Goldman Sachs, per Zitron, estimated hyperscalers would need about $360 billion in brand new AI revenue just to break even on 2026 to 2027 capex, and about $425 billion to earn a 10% return on invested capital. Current AI revenue is $140 billion to $170 billion if lucky, he said. Gartner, which Zitron noted had hyped neoclouds as essential in October 2025, now projects 80% of neoclouds will be dead by 2030, and estimates AI data center owners need to generate a cumulative $8.5 trillion through 2030 to cover announced capital spending, financing costs and a 12% return, Zitron said.