"Significant AI investments despite unknown revenue mirrors the '21, '22 Metaverse spending." This stark observation, highlighted by Jason Helfstein, Oppenheimer's Head of Internet Research, encapsulates the core concern driving his firm's recent downgrade of Meta Platforms. The market, it seems, is experiencing a sense of déjà vu, wary of another massive capital expenditure cycle with an uncertain path to monetization.
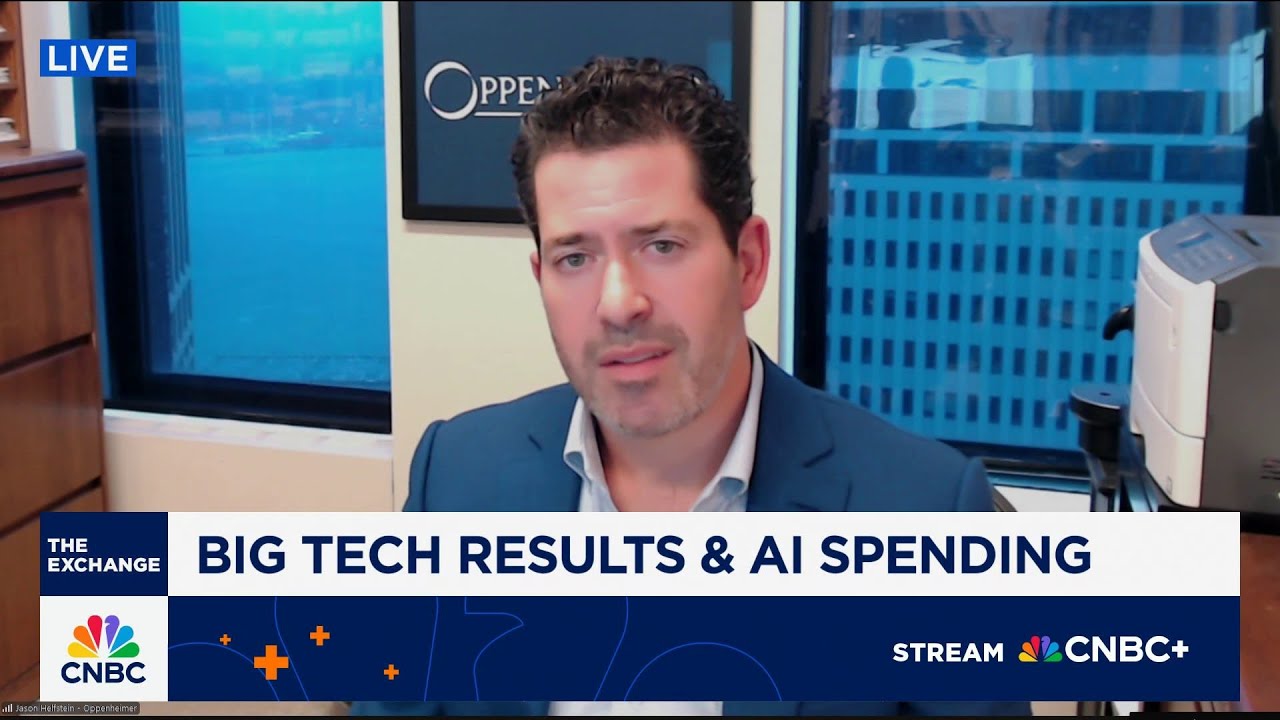
Helfstein spoke with CNBC's 'The Exchange' to discuss Oppenheimer's downgrade of Meta, drawing critical distinctions between its investment strategy and that of Alphabet, and probing the wider implications for investor sentiment. The conversation centered on Meta's aggressive push into artificial intelligence and the market's struggle to rationalize such significant spending without clear, near-term revenue visibility.
Meta has committed to substantial capital expenditures, projecting figures around $72 billion for the current year, with further increases anticipated next year. This immense investment is channeled into advanced AI initiatives, including the pursuit of Artificial General Intelligence (AGI) and superintelligence. However, the connection between these ambitious projects and Meta's primary advertising revenue streams remains conspicuously vague. Helfstein directly questioned this link, stating, "It's unclear how that's going to drive the advertising business." This lack of a direct, discernible return on investment is a critical point of friction for shareholders.
The market's memory is long, and the echoes of Meta's costly, yet financially underwhelming, Metaverse pivot are fresh. Investors, having seen billions poured into a vision that has yet to materialize into a significant profit driver, are understandably cautious. The current wave of AI spending, while strategically crucial for future relevance, is perceived by some as another speculative bet, requiring a leap of faith that many are unwilling to make without more concrete financial projections.
This sentiment is particularly pronounced when comparing Meta to its big tech peer, Alphabet. While both companies are heavily invested in AI, Alphabet offers a more predictable earnings profile and is viewed as having superior expense discipline. Helfstein underscores this divergence: "We're forecasting Meta is only going to grow earnings per share 3% next year, whereas, you know, Google should be 25, 26%." This considerable gap in projected earnings growth makes Meta's equivalent valuation multiple harder to justify, placing it in a less favorable light for investors seeking reliable financial performance.